Entry Pay vs Lifetime Pay: Career Earnings Comparison (Guide)
A few years ago, I sat down with a young man named Marcus who was facing a choice that felt like a million-dollar gamble. He had two job offers on the table. One was a specialized labor role in a hazardous environment that offered a starting salary of $75,000. The other was a junior corporate track position that paid just $48,000. Marcus was leaning toward the higher paycheck because he wanted to buy a house and start his life. However, when we sat down to look at the 40-year projections, the numbers told a story he didn’t expect. By the time Marcus reached age 45, the lower-paying job was projected to outearn the high-start job by over $60,000 per year. By retirement, the “lower-paying” path would have generated $1.8 million more in total gross earnings. This realization changed his entire career strategy and highlights why looking at entry pay alone is a dangerous financial move.
Understanding the Difference Between Entry and Lifetime Pay
Entry pay is the initial salary you receive when you first start a career, while lifetime pay is the total amount of money you earn over a 40-year working period. Entry pay focuses on immediate needs, but lifetime pay accounts for raises, promotions, and the long-term growth of your income.
When you look at a job offer, the first number you see is the annual salary. This is your entry pay. For many people, this number is the only one that matters because it determines their current lifestyle. However, as an ROI expert, I view entry pay as just the “starting line.” It tells you where you begin, but it says very little about where you will finish.
Lifetime pay is a much more important metric for long-term wealth. It represents the “marathon” of your career. To calculate this, we look at your likely earnings from age 22 to 62. We factor in how much your pay will grow each year. Some jobs start high but stay flat. Other jobs start low but climb quickly. Understanding the difference helps you avoid “income plateaus” where your earnings stop growing just as your life expenses, like a mortgage or family costs, begin to rise.
The High-Start Linear Career Path
A linear career path is a job that offers a high starting salary but has very limited room for pay increases over time. These roles often involve specialized trades, hazardous labor, or roles where pay is tied to a fixed hourly rate or a strict union scale.
I often see students drawn to linear career paths because the “day one” money is excellent. Think of roles like certain types of commercial driving, basic technical trades, or hazardous site work. These jobs might pay $70,000 right away. This is much higher than the average entry-level office job. For a 22-year-old, this feels like a massive win.
The problem is the growth ceiling. In these roles, you are often paid for your time or a specific physical skill. Once you master the skill, there are few “levels” to climb. Your raises might only be 1% or 2% per year to keep up with inflation. Because the growth is flat, your purchasing power stays the same for decades. In my analysis, these roles are great for short-term goals, but they often fall behind in total lifetime earnings because they lack “promotional leaps.”
- Starting pay is often 20% to 40% higher than average.
- Annual raises are usually small and tied to cost-of-living adjustments.
- There are few management tiers or higher-level roles to move into.
- The physical demands may make it harder to maintain the same income in later years.
The Low-Start Exponential Career Path
An exponential career path is a role that starts with a lower salary but offers significant opportunities for rapid pay increases and promotions. These are typically found in professional services, technology, and corporate environments where experience and leadership lead to higher pay grades.
Many cost-conscious students are afraid of taking a job that pays $45,000 or $50,000. They worry they won’t be able to pay their bills. However, these “low-start” roles often have an exponential growth curve. In these fields, your value to an employer increases as you gain experience and move into management.
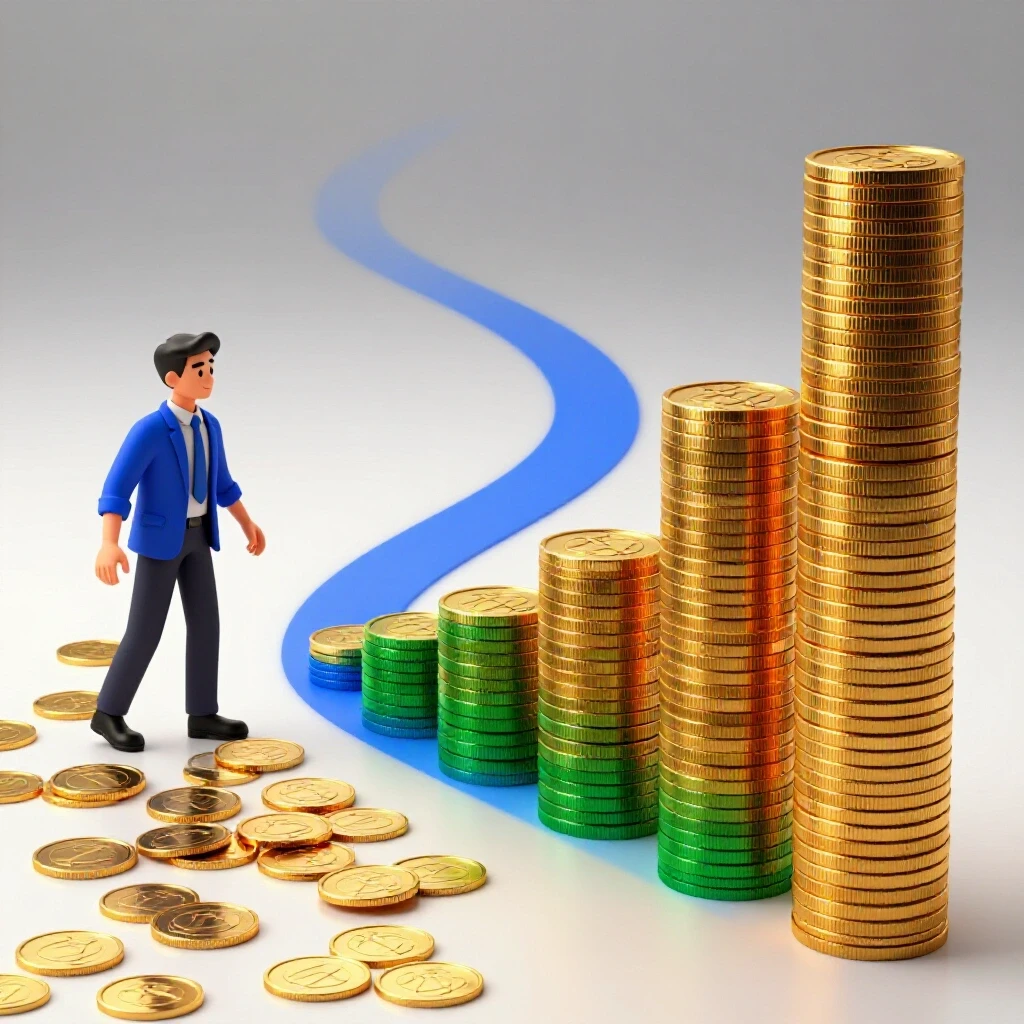
In an exponential path, you might see a 5% to 10% raise every couple of years as you move from a junior role to a senior role. These jumps are called “promotional leaps.” While you start behind the person in the linear trade, your “slope” is much steeper. Interestingly, the data shows that the “crossover point”—the moment your annual salary passes the linear worker—often happens within the first seven to ten years of your career.
- Starting pay may feel low, often near the median for all entry-level roles.
- Pay increases are tied to performance, new skills, and title changes.
- High upward mobility allows for significant jumps in income every 3 to 5 years.
- The work is often less physically demanding, allowing for a longer career.
Calculating the 40-Year Earnings Horizon
The 40-year earnings horizon is a mathematical model used to estimate total career income by projecting annual raises and promotions over four decades. This model helps compare the total financial value of different career choices rather than just comparing starting salaries.
To show you how this works, I have built a comparison model. Let’s compare “Career A” (High Start, Linear Growth) and “Career B” (Low Start, Exponential Growth).
Career A starts at $70,000 with a steady 2% annual increase. Career B starts at $50,000 but averages a 6% annual increase through a mix of raises and promotions.
| Year of Career | Career A (Linear) | Career B (Exponential) |
|---|---|---|
| Year 1 | $70,000 | $50,000 |
| Year 5 | $75,770 | $63,123 |
| Year 10 | $83,655 | $84,473 |
| Year 20 | $101,975 | $151,272 |
| Year 30 | $124,308 | $270,900 |
| Year 40 | $151,530 | $485,146 |
| Total Lifetime | $4,228,245 | $7,738,103 |
As you can see, the “tipping point” happens around Year 10. Before Year 10, the person in Career A was making more money. But after Year 10, Career B takes off. By the end of a 40-year career, the person in the exponential path has earned over $3.5 million more. This is the “hidden” value that most people miss when they only look at the ROI of a college degree based on the first year out of school.
The Power of Promotional Leaps and Raises
Promotional leaps are significant increases in salary that occur when an employee moves to a higher-level position or takes on more responsibility. These leaps are the primary engine for lifetime wealth and distinguish high-growth careers from stagnant ones.
Why does Career B end up so far ahead? It comes down to compounding growth. When you get a 6% raise on a $100,000 salary, it is much more impactful than a 2% raise on a $100,000 salary. In high-growth fields, you aren’t just getting cost-of-living adjustments. You are getting paid for your increased expertise.
In my years of mentoring, I have found that the best value degrees are those that provide a foundation for these leaps. For example, a degree in a field like health administration or data science might not have the highest starting pay compared to some dangerous trades. However, the path from “Analyst” to “Manager” to “Director” provides multiple opportunities for $15,000 to $30,000 pay jumps. These leaps are what create the massive gap in lifetime earnings.
- Raises of 1–2% usually only cover inflation and don’t build wealth.
- Promotional leaps of 10% or more significantly change your financial trajectory.
- Changing companies every few years in an exponential field can often lead to even larger jumps.
- Skills that are “scalable,” such as leadership or technical architecture, lead to the biggest leaps.
Retirement Matching and the Wealth Gap
Retirement matching is a benefit where an employer contributes money to your retirement account based on a percentage of your salary. Because these contributions are tied to your pay, a higher lifetime salary results in a much larger retirement nest egg.
There is another hidden factor in the “Entry vs. Lifetime” debate: employer benefits. Most professional-track jobs offer a retirement match, often around 3% to 6% of your gross pay. If you are in a high-growth career, your employer’s contribution grows every time you get a raise or a promotion.
If you earn $50,000, a 5% match is $2,500. If you earn $150,000 later in your career, that same 5% match is $7,500. Over 40 years, the person in the exponential career path receives hundreds of thousands of dollars more in “free money” from their employer. When you add the investment growth on that money, the gap between the two career paths becomes even wider. This is a key part of the debt-to-income ratio education that students need to hear. It isn’t just about the paycheck; it is about the total compensation package over time.
- Higher salaries lead to higher employer retirement contributions.
- Compounding interest on those contributions creates a massive wealth advantage.
- Professional tracks often include better health insurance and bonuses.
- These “fringe benefits” can add 20% to 30% to your total lifetime value.
How to Predict Your Own Salary Trajectory
Predicting a salary trajectory involves researching the median pay for both entry-level and mid-career professionals in a specific field. By comparing these two data points, you can determine if a career path is linear or exponential.
To make a smart choice, you need to look at more than just one number. I recommend a three-step process for evaluating any degree or career path. First, find the median starting salary. Second, find the median salary for someone with 10 to 15 years of experience in that same field. Third, calculate the growth percentage between those two points.
If the mid-career salary is only 20% higher than the starting salary, you are looking at a linear path. If the mid-career salary is 100% higher (double) the starting salary, you have found an exponential path. Tools like the College Scorecard and the Bureau of Labor Statistics (BLS) are perfect for this. They allow you to see what people are actually earning a decade after they finish their education. This is how you find the true worth of a master’s degree or a specific bachelor’s program.
- Visit the College Scorecard: Look up your school and major to see the median earnings 10 years after enrollment.
- Check the BLS Occupational Outlook Handbook: Look at the “Pay” section for your target career. Compare the “lowest 10 percent” (entry) to the “median” and “highest 10 percent” (senior).
- Use a College ROI Calculator: Plug in your expected starting and mid-career salaries to see the 40-year total.
- Interview Professionals: Ask people in the field, “What does the pay look like for someone with 20 years of experience compared to a rookie?”
Practical Tips for Cost-Conscious Decision Makers
Cost-conscious decision-making requires balancing the immediate need for a paycheck with the long-term goal of wealth accumulation. It involves choosing paths that offer the best “slope” for income growth while minimizing the time it takes to reach the crossover point.
I know that the fear of debt is real. Many parents and students want the “safe” bet of a high starting salary. But “safe” in the short term can be “risky” in the long term. If you choose a job that never grows, you may find yourself struggling to keep up with the cost of living 20 years from now.
The best strategy is to look for “high-floor, high-ceiling” careers. These are roles that have a decent starting pay but also have a clear path to six figures. For example, nursing often has a high entry-level salary and a very high ceiling if you pursue advanced certifications or management. This provides the best of both worlds: immediate financial stability and long-term growth.
- Don’t be blinded by a high starting salary in a field with no growth.
- Value “promotability” as much as you value the starting paycheck.
- Look for industries that are growing, as they tend to offer more promotional leaps.
- Remember that the first 10 years are about learning, while the next 30 are about earning.
Common Mistakes to Avoid When Comparing Pay
Common mistakes in career planning include ignoring inflation, failing to account for physical career longevity, and focusing only on the “sticker price” of a starting salary. These errors lead to poor long-term financial outcomes.
One of the biggest mistakes I see is failing to account for “career duration.” A high-paying hazardous job might only be sustainable for 15 or 20 years before the physical toll becomes too great. If you have to take a pay cut at age 45 because you can no longer do the work, your lifetime earnings will plummet.
Another mistake is ignoring the “opportunity cost” of not having a degree or certification that allows for management roles. You might save money now by skipping specialized training, but you lose the ability to jump to those higher pay grades later. Always ask yourself: “Where will I be at age 50 in this career?” If the answer is “doing the same thing for roughly the same pay,” you should reconsider the path.
- Mistake 1: Choosing a job solely for the signing bonus or high entry pay.
- Mistake 2: Assuming that a 2% raise every year is “good enough.”
- Mistake 3: Forgetting that professional roles often have better long-term stability.
- Mistake 4: Not factoring in the value of employer-sponsored benefits and matching.
Action Plan: Steps to Maximize Your Lifetime ROI
A lifetime ROI action plan is a step-by-step strategy to select a career path that balances immediate financial health with maximum 40-year earnings. It involves data research, financial modeling, and strategic career alignment.
To ensure you are making a data-driven decision, follow this checklist. I have used this with hundreds of mentees to help them find clarity. It moves you from “guessing” to “knowing” the value of your education and career choices.
- Identify three potential career paths: Mix “high-start” and “high-growth” options.
- Research the “Income Slope”: Use BLS data to find the 10th percentile and 90th percentile pay for each.
- Map the 40-year journey: Use a simple spreadsheet to project a 2% growth for linear roles and a 5–6% growth for exponential roles.
- Identify the Crossover Point: Note the year when the high-growth path starts making more annually than the high-start path.
- Evaluate the “Total Package”: Research which fields typically offer the best retirement matching and bonuses.
- Choose the path with the highest Net Present Value: This is the path that gives you the most total wealth over time, adjusted for the value of money today.
By following this method, you aren’t just looking for a job. You are building a financial engine. Marcus, the student I mentioned earlier, eventually chose the lower-paying corporate track. It was hard for the first three years, but by year five, he received a promotion that put him ahead of his peers in the trades. Today, he is on track to hit his million-dollar milestones much faster than if he had taken the “easy” money at the start.
Frequently Asked Questions
What is a good debt-to-income ratio for a college degree?
A generally safe rule is that your total student debt should not exceed your expected first-year salary. For example, if you expect to earn $50,000 in your first year, you should try to keep your total debt below that amount. This ensures that you can manage your payments while still benefiting from the higher “exponential” growth of a professional career path.
Why does lifetime pay matter more than starting salary?
Lifetime pay matters more because most of your wealth is built in the second half of your career. Small differences in annual growth rates compound over 40 years. A job that starts $10,000 lower but grows 3% faster each year will eventually provide millions of dollars more in total income and retirement savings.
How can I find reliable salary data for my specific major?
The best resource is the U.S. Department of Education’s College Scorecard. It provides median earnings for graduates of specific programs at specific schools one, two, and even ten years after graduation. You can also use the NCES (National Center for Education Statistics) and Payscale’s ROI reports to see how different degrees perform over a 20-year horizon.
Is a master’s degree worth the investment for lifetime pay?
The worth of a master’s degree depends on the “pay ceiling” of your field. In fields like education, nursing, or engineering, a master’s degree often unlocks higher-tier management roles or specialized pay scales that provide a significant “promotional leap.” If the degree doubles your mid-career earning potential, the lifetime ROI is usually very high.
What are “linear” vs “exponential” careers?
A linear career has a flat pay structure where your income only increases slightly with inflation (e.g., some manual labor or fixed-rate service jobs). An exponential career has a steep pay structure where your income grows rapidly as you gain experience, certifications, and management responsibilities (e.g., tech, finance, or healthcare administration).
How do raises and promotions affect my 40-year ROI?
Raises and promotions are the most powerful factors in lifetime ROI. A promotion that comes with a 15% pay jump is worth significantly more than a decade of 2% cost-of-living raises. Careers that offer frequent opportunities for these “leaps” will always outperform careers with steady but slow growth.
When does a “low-start” career usually pass a “high-start” career in pay?
In most professional fields, the “crossover point” happens between year 7 and year 12. While the high-start worker earns more in the first few years, the high-growth worker’s steeper pay trajectory eventually leads to a higher annual salary that stays higher for the rest of their career.
Should I choose a trade or a degree based on these numbers?
The choice depends on your personal goals and the specific data for those paths. Some high-end trades have very high ceilings and behave like exponential careers. However, many trades are linear. You must compare the 40-year projected earnings of the specific trade against the 40-year projected earnings of the degree-based career to see which offers the better total return.
(This article was written by one of our staff writers, Benjamin Carter. Visit our Meet the Team page to learn more about the author and their expertise.)